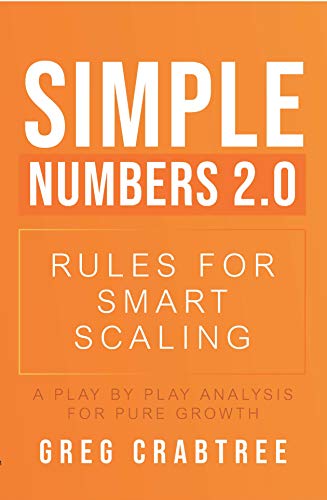
Simple Numbers 2.0
Rules for Smart Scaling
A private company is an investment that should earn at least fifty percent pretax return on the capital the owners put in, and every growth decision should be judged against that standard rather than against revenue.
A book summary and review by Bruce Eckfeldt
Overview
Simple Numbers 2.0 is Greg Crabtree’s follow-up to his 2011 book Simple Numbers, Straight Talk, Big Profits! The first book taught owners to pay themselves a market wage, target pretax profit, keep two months of operating expenses in cash, and measure labor against gross margin. The sequel moves the focus from profitability to return on invested capital. Crabtree credits David Wessels of the Wharton School, whose teaching he heard while chairing the Entrepreneurs’ Organization program there, with shaping how he applies the concept to private companies.
The book has two parts. Part 1 asks the owner to think like an investor, value the business as an investment, and decide when to keep it and when to sell. Part 2 covers the two levers that drive the return: profit and capital. Crabtree introduces four types of capital, the idea of a capital signature for each business model, launch capital as the cost of every growth bet, targets set before forecasts, labor efficiency ratios, segment analysis, and value-based spending in place of budgets.
The argument rests on data from the companies Crabtree’s firm models, not on academic research. He writes from the view of a CPA who wants owners to read their numbers the way an investor would.
A private company is an investment that should earn at least fifty percent pretax return on the capital the owners put in, and every growth decision should be judged against that standard rather than against revenue.
Chapter Summaries
Chapter 1: Three Simple Rules for Business Success
The opening chapter sets the three tests every business and every growth move must pass. Crabtree returns to them throughout the book as the go or no-go filter for new spending.
- Rule one is to figure out what the market needs. Revenue and new customers are the evidence the market accepts the offer.
- Rule two is to find a way to deliver it profitably. Profit is measured after the owner is paid a market wage for the role they actually perform.
- Rule three is that, for the amount of capital required, the business must produce a pretax profit equal to at least fifty percent return on invested capital. The rule makes capital, not revenue, the scorecard.
Chapter 2: Think Like an Investor
Crabtree argues that the most common error owners make is failing to treat their company as an investment vehicle. He sorts businesses into three value plays and defines invested capital narrowly enough that an owner can compute it.
- The three value plays are run to harvest, harvest to premium sale, and build to sell. Run to harvest is the most common. Crabtree says these businesses struggle to pass about five million in revenue and usually sell for four to five times EBITDA, much of it on an earnout. Premium sales go to businesses with sticky customers, contracted revenue, or hard-to-assemble teams.
- Invested capital is the money the owners put in plus sweat equity, meaning work done for less than a market wage. Debt is not invested capital in Crabtree’s definition. It is a placeholder that must eventually be replaced with real capital.
- Across hundreds of businesses Crabtree has studied, every properly capitalized company earning less than fifty percent ROIC struggled with cash flow. The exceptions held more than two months of operating expenses in cash. He reports that seventy-five percent ROIC is the most common figure among skilled operators, rising toward ninety percent above five million in revenue.
- In a fifty-company data set from his practice, revenue grew fourteen to twenty percent a year for three years with no outside capital. The companies also distributed twenty-seven to twenty-nine percent of profits each year. Crabtree uses this to challenge the belief that growth requires outside money. He also notes that owners took roughly a third of profits out, mostly for consumption.
Chapter 3: Valuing Your Business as an Investment
The chapter offers a formula-based economic value for buy-sell agreements and partner buyouts, then explains why market value can run higher.
- Economic value is the last three years of pretax net income plus equity at the date of sale. Crabtree built the formula by asking how many years of after-tax profit owners would give up to buy out a fifty percent partner. People who had never done it said two to three years. People who had done it said five.
- Using all after-tax profit, his example buyout takes fifty-one months. In practice he sees four to six years. A buyout can be paid off faster only when growth does not need more receivables or inventory.
- Market value can exceed economic value because, in Crabtree’s phrase, money chases easy while entrepreneurs overcome hard. He notes that buyer theses still work less than half the time.
- Insider sales rarely work from cash flow alone beyond ten years of amortization. Crabtree notes that the SBA usually lends only seven years for this kind of debt. Above five times net income, outside capital is almost always needed. He also describes strip sales and thorn-in-the-side acquisitions as other routes to value.
Chapter 4: When to Keep, When to Sell
Crabtree replaces the question of market value with a narrower one: will the after-tax proceeds of a sale replace the pretax profit the owner gives up?
- Replacement return is the yield the after-tax sale proceeds must earn to match the business’s current pretax profit. His example covers offers at five, seven, and ten times net income. The required replacement return ranges from about thirteen to twenty-seven percent.
- Crabtree puts expected real estate yields at eight to fifteen percent. An offer at five times net income makes economic sense only if the owner has another business to reinvest in. An economic green light comes only when the required replacement return falls below fifteen percent.
- Use ROIC to decide whether to reinvest, and replacement return to decide whether to sell. According to Crabtree, the concept has led owners to postpone sale talks until an offer clears the fifteen percent threshold.
Chapter 5: Matching Capital to the Three Primary Business Models: Make Stuff, Sell Stuff, or Do Stuff
The chapter argues that every business is some mix of making, selling, and doing, and that each model has a distinct profit and capital pattern. Crabtree redraws the balance sheet around four types of capital to make that pattern visible.
- Cost of goods sold is a pass-through. A distributor with forty million in revenue at a thirteen percent gross margin is really a five-point-three-five-million-dollar inventory management company. Gross margin, not revenue, is the true top line, especially when gross margin is below forty percent.
- The four types of capital are trade, infrastructure, buffer, and launch. Trade capital is working capital with cash and short-term debt removed: receivables, inventory, and work in progress, minus payables, accrued expenses, and deferred revenue.
- If trade capital as a percentage of revenue is below net income as a percentage of revenue, the company is in a cash-free growth zone. If it is above, the company must grow by the base camp method. It grows as far as cash and credit allow, pauses to let cash catch up, then grows again.
- Buffer capital is Crabtree’s cash standard: two months of operating expenses on hand and nothing drawn on the line of credit. He found it by searching four years of data for the deepest monthly cash dip. Companies that met the standard entered 2008 with cash, and he reports that many had their most profitable years in the recession that followed.
Chapter 6: Launch Capital for Growth Phase: The Magic Pixie Dust of Business
Launch capital is the operating losses and extra spending a company absorbs before a new activity pays off. Crabtree argues that owners make these bets constantly without naming them, so they never hold them to a return.
- Every new spend, whether marketing, a key hire, or a consultant, is a bet. It should be expected to raise annual profit by at least fifty percent of the amount spent. Unlike money used to fund receivables or repay debt, a failed catalytic spend cannot be recovered.
- The black hole runs from one to five million in revenue, or in gross margin in some models, and is darkest around three million. A profitable company at three million is usually running on an unsustainable labor structure. The only options are to pull back or push through to five million with better management.
- Simple Numbers reporting uses rolling twelve-month data as the main source of truth and rolling three months for pacing. Year to date is useful only for estimating taxes. A month is too noisy a unit for decisions.
- In one expansion example, Crabtree tags six hundred ninety thousand dollars of spending that was not needed to keep the current business running. He then raises the next year’s profit target by half that amount. Making the bet explicit turns a vague expansion into an accountable one.
Chapter 7: Target First, Then Forecast: Beyond the Budgeting Mindset
The chapter shows how to set a profit target at minimum, target, and stretch levels, then work up through the ratios to see whether the revenue required is realistic.
- There are two labor plays. A company either flexes labor to what it sells or sells enough to cover the labor it has committed to. In the example, a contractor kept its direct labor through a down year. The overstaffing, extra marketing, new management hires, and consultants added up to seven hundred forty-one thousand dollars of launch capital. Profit rose by one million dollars, a return of one hundred thirty-five percent.
- Pay should chase performance. A new high in management labor efficiency becomes the standard and caps raises, bonuses, and new management hires until the team produces at that level.
- Crabtree’s most successful owners have dropped the word revenue and moved sales incentives to contribution margin, or to gross margin if needed. That makes salespeople sell what the delivery team does best.
- In a low-margin business, each added dollar of management labor needs nearly six dollars of new gross margin to hold profitability. In higher-margin businesses it needs six to ten dollars of revenue. Crabtree argues that ROIC is what scales. Operating margins rarely improve past five million in revenue.
Chapter 8: Using Labor Efficiency Ratio as a Management Tool
Labor efficiency ratio is the book’s core management metric. It treats labor as an output to be measured, not a cost to be minimized.
- Direct labor efficiency ratio is gross margin divided by direct labor. Management labor efficiency ratio is contribution margin divided by management labor. Revenue is excluded from both because pass-through costs vary by model and customer.
- Each person goes entirely into one bucket. Anyone spending half or more of their time doing what the business sells is direct labor. Wages are counted without payroll tax and benefits. Crabtree warns against benchmarking against industry data unless the method is known. The best standard is the company’s own record performance.
- In the Aspire to Serve case, the company missed its plan. It cut unprofitable services and customers, then capped hiring and raises until direct labor efficiency reached three dollars and fifty cents per quarter. The owner had to borrow personally to stabilize cash, which Crabtree uses to show the cost of trying to grow out of a hole.
- The career labor efficiency curve has three zones. In the training zone, pay exceeds output. In the chasing zone, output exceeds pay and raises should follow proven performance. In the replacement zone, pay overtakes output again, and the role or pay should change before the drama starts.
Chapter 9: Segment Analysis: The Power Tool to Scale Profitably
Crabtree argues that company-wide numbers hide which products, locations, or teams create value. He shows how to report each segment at three levels without getting lost in cost allocations.
- Segment reporting has three levels: gross margin, contribution margin, and net operating income by segment. Most segments can stop at contribution margin unless there is a formal division or location structure.
- In the retail example, the store with the most revenue and profit dollars was not the best investment. A store with tightly focused inventory turning five times a year, and a landlord-funded buildout, earned the best return.
- In a field services example, recurring maintenance had five days of receivables, against forty-five for project work and seventy-five for construction. Crabtree says this is why private equity pays for recurring revenue. Raising labor efficiency on projects from 2.22 to 2.84 more than doubled the return on trade capital.
- Across three service teams, the fixed-price productized team produced the most margin even though the hourly project team logged the most hours. Crabtree’s point is that hourly billing ends up either giving away expertise or charging for ignorance.
Chapter 10: Value-Based Spending: How to Avoid Budgeting Mindset Traps
The closing chapter argues that a budget is a license to spend while a forecast is a license to make money. Crabtree replaces line-item budgets with a value test on every recurring cost.
- Annual budgets cannot adjust midyear. A company that falls behind in the first quarter tends to stop managing to the budget, or keeps spending to it while revenue and margin fall. Crabtree points to Jack Stack and the Great Game of Business approach for the alternative, which is accurate forecasting.
- Ongoing expenses are reviewed by asking whether the company still gets value from each item. Rolling twelve-month trends in facilities, marketing, and other operating expenses show where to look.
- The practical checks include recording card charges by vendor, ranking spend by vendor every quarter, auditing recurring card and ACH charges, and keeping the chart of accounts short.
- As a rule of thumb, each non-labor dollar added for productivity should produce two dollars of revenue. Branding spend should be tracked separately from transactional marketing.
About the Author
Greg Crabtree is a CPA who founded the accounting firm Crabtree, Rowe and Berger in Huntsville, Alabama, in 1986. He started it after five years at a regional accounting firm and three years as vice president of operations and controller at a bank. After the firm made the Inc. 5000 list in 2019, it merged with Carr, Riggs and Ingram, a top-25 national accounting firm. His first book, Simple Numbers, Straight Talk, Big Profits!, was published in 2011. He wrote the labor efficiency chapter in Verne Harnish’s Scaling Up and chaired the Entrepreneurs’ Organization executive program at the Wharton School.
His credibility here comes from modeling the financials of many owner-led companies and from being an entrepreneur himself. His benchmarks come from his firm’s own data, not from published research. The book does not report the size or makeup of that data, apart from the fifty-company set described in the second chapter.
Key Takeaways
1) Return on invested capital is the scorecard, and fifty percent pretax is the floor.
Crabtree’s main move is to make the owner judge the business the way an investor would judge any other asset. Profit matters only in relation to the capital needed to produce it. A business that clears fifty percent pretax ROIC can fund its own growth, pay distributions, and survive downturns. A business below that line, at proper capitalization, is fragile however good its revenue looks.
- Invested capital is owner money plus sweat equity. Debt is excluded as a placeholder.
- Seventy-five percent ROIC is the most common result Crabtree sees among skilled operators.
- High ROIC from heavy borrowing is a false signal that fails when credit tightens.
2) Gross margin is the real top line, and revenue is the most slippery number on the P and L.
Cost of goods sold flows through the business without creating value inside it. Measuring labor, sales incentives, and comparisons against revenue rewards volume that may not produce margin. Measuring against gross margin and contribution margin shows what the company actually produces.
- A forty-million-dollar distributor at thirteen percent gross margin is a five-million-dollar company in economic terms.
- Sales incentives tied to contribution margin push salespeople to sell what the delivery team does best.
- Comparisons across industries only make sense on gross margin.
3) Every business has a capital signature that sets how fast it can grow without burning cash.
Two companies with the same margin can have opposite cash outcomes because of how their receivables, inventory, payables, and deferred revenue interact. Comparing trade capital and net income, each as a share of revenue, shows whether growth produces cash or consumes it. That tells the owner whether to grow continuously or in base camp stages.
- Trade capital is working capital with cash and short-term debt removed.
- Corporate payment terms combined with carried inventory is the worst capital signature.
- Deferred revenue can make a services firm cash-free in growth until it disappears.
4) Growth spending is a bet, and unnamed bets are never held to account.
Launch capital covers every expense taken on to move the business beyond its current level: overstaffing ahead of demand, new management, marketing pushes, and consultants. Crabtree argues these bets are where wealth is made or lost. Unlike funding receivables or paying down debt, a failed bet cannot be recovered. Naming the bet and requiring a fifty percent return turns experimentation into discipline.
- Incremental bets over the life of a business matter more than the initial investment.
- In Crabtree’s contractor example, a seven-hundred-forty-one-thousand-dollar bet returned one hundred thirty-five percent.
- Marketing returns decay as the market gets used to the message, so spend levels must be tested again.
5) Labor is measured as an output, and pay chases performance.
The labor efficiency ratios recast payroll from a cost to cut into a production rate to manage. Direct labor is held to gross margin and management labor to contribution margin. A record ratio becomes the standard for future raises and hires. That gives the CEO a defensible answer when the team asks for more pay or more staff.
- Each added dollar of management labor needs six to ten dollars of new revenue to hold profitability.
- The best benchmark is the company’s own record, not industry surveys.
- The career curve makes the replacement zone visible before it turns personal.
6) The black hole between one and five million is a management problem disguised as a growth problem.
Crabtree places the hardest stretch of private company growth at around three million in revenue. At that point the founder’s informal labor structure stops working and the management team is too thin. The only options are to pull back or invest in management labor and absorb the dip. Treating the management upgrade as launch capital lets the owner fund it on purpose and measure the return.
- A profitable company at three million is often running on an unsustainable labor structure.
- The fix is rarely quick and often costs a losing year.
- Past five million, scaling depends on market penetration more than on margin gains.
7) Keep or sell is a replacement return calculation, not a valuation contest.
Owners tend to judge sale offers by the multiple. Crabtree reframes the decision around the yield the after-tax proceeds would need to earn to replace current pretax profit. Because a well-run private company can earn fifty percent or more on its capital, most offers fail this test unless the owner has a better reinvestment ready or a personal reason to exit.
- Expected real estate yields of eight to fifteen percent set the realistic alternative for most owners.
- An economic green light comes only when the required replacement return is below fifteen percent.
- The formula-based economic value gives partners a usable price for buy-sell agreements without an appraisal.
Strengths and Limits
The book’s strength is that it turns corporate finance ideas into tools a private company owner can run on a spreadsheet. The four types of capital, the comparison of trade capital and net income as shares of revenue, and the labor efficiency ratios each change a decision the owner actually faces. The launch capital framework adds something most financial literature for small companies lacks: a way to make growth spending accountable without a budget. Crabtree’s examples, including the auto service store owner Bob, the contractor’s launch bet, the Aspire to Serve recovery, and the retail and service segments, show the math rather than only stating the rule.
The limits come from the evidence and the definitions. Benchmarks such as the fifty percent ROIC floor, the two-month cash standard, and the six-to-ten-dollar management labor rule come from the firm’s own data, and the book does not describe its size or method. Excluding debt from invested capital differs from standard corporate finance and pushes ROIC above figures in public company literature, so the fifty percent standard cannot be compared with outside benchmarks. Many examples are reconstructions from Crabtree’s practice that depend on tables summarized in the text. The predictable failure is that a leadership team adopts the ratios as targets without the clean data, consistent labor classification, and rolling reports the ratios require. The numbers then turn into a new budget to negotiate rather than a measure of reality.
My Take
The diagnosis holds. Founder-CEOs in the five-to-fifty-million range still run on revenue and the P and L, and rarely look at the balance sheet. Crabtree’s reframing around capital and labor output is the most usable finance lens I know for this stage. The black hole description matches what happens at the three-to-five-million transition. It also matches the repeat version that hits again when a company outgrows its first layer of managers.
The book plays differently by model. In a services firm, labor efficiency is close to the whole story, and the segment work on hourly versus fixed-price teams is worth the price of the book. In a distribution or manufacturing company, the capital signature chapter matters more, because trade capital is where the cash goes. In venture-backed SaaS, the fifty percent ROIC floor and the self-funding bias collide with a deliberate strategy of spending outside capital ahead of revenue. The launch capital logic still applies, but the hurdle does not.
The most credible outside objection comes from the corporate finance tradition represented by Tim Koller and his McKinsey colleagues in Valuation. They define invested capital as the operating capital funded by debt and equity together. On that definition, Crabtree’s ROIC figures are inflated by leaving out debt and cannot be compared with a cost of capital. I think the objection is right on method and less important in practice. Crabtree is not trying to price a company. He is trying to keep founders from growing into a cash crisis, and his cash standard does that.
The book leaves the CEO with good numbers and a thin plan for the leadership team. Labor efficiency and segment data only change behavior when managers understand them and have a stake in moving them. Jack Stack’s The Great Game of Business completes that side, with critical numbers, open-book huddles, and a bonus plan tied to the same economics. Read Crabtree to choose the numbers and Stack to get the team playing to them.
Discussion Questions
For CEOs
- What was our pretax return on invested capital over the last rolling twelve months, using Crabtree’s definition of owner money plus sweat equity?
- Is our trade capital as a percentage of revenue above or below our net income as a percentage of revenue, and does that match how we plan growth?
- Do we hold two months of operating expenses in cash with nothing drawn on the line, and if not, what is the shortfall in dollars?
- Which of the three value plays describes our business today, and which one are we actually building toward?
- What growth bets did we make in the last year that were never named as launch capital, and what did each return?
- If an offer arrived next month at seven times net income, what replacement return would the proceeds need, and could we actually earn it?
- Am I paying myself a market wage for the role I really perform, and how does that change our true profit?
- Which management hires in the last two years have earned their keep at six to ten dollars of new revenue per dollar of pay?
For Teams
- Who on our team is direct labor and who is management labor under Crabtree’s whole-person rule, and do we all agree on the list?
- What is our record direct labor efficiency ratio on a rolling twelve-month basis, and what would it take to match it this year?
- Which customers, services, or locations produce the lowest contribution margin, and what would we change if we saw that data monthly?
- Are our sales incentives tied to revenue, gross margin, or contribution margin, and what behavior does that create?
- Which recurring expenses would no one miss if we stopped them for ninety days?
- Where are we billing by the hour in work we could package at a fixed price?
- What is the next profit target we would have to hit to justify the hires we are asking for?
- Which team members are in the training, chasing, or replacement zone, and what conversation does each zone call for?
Practical Tools
1. Owner ROIC Calculation
Crabtree’s third rule says every business must earn at least fifty percent pretax return on the capital its owners put in. Most founders have never calculated the number because standard financial statements do not present it. Run this calculation once on the last three fiscal years to establish a baseline, then each quarter on a rolling twelve-month basis. It also belongs at the start of any planning cycle in which the company expects to reinvest profits.
How it works:
- Total the capital the owners have put in since founding, plus any years an owner worked below a market wage for the role, valued at the difference.
- Add retained after-tax earnings to arrive at invested capital at the start of each year.
- Restate pretax profit after charging every working owner a market wage for the role they perform.
- Divide restated pretax profit by beginning invested capital for each year.
- Compare the result to fifty percent. Note separately how much debt and how much cash above two months of operating expenses sit on the balance sheet, since both distort the number.
The leadership team can say what return the business earns on its owners’ money and whether that return is rising or falling. The next reinvestment discussion starts from that figure instead of from revenue growth.
2. Capital Signature Check
Crabtree shows that the interaction of receivables, inventory, payables, and deferred revenue decides whether growth produces or consumes cash. This check tells the CEO whether the company can grow continuously or must grow in base camp stages. Run it before setting an annual growth target, before changing customer payment terms, and whenever cash falls while profit rises.
How it works:
- Compute trade capital: receivables plus inventory plus work in progress, minus payables, accrued expenses, and deferred revenue.
- Express trade capital as a percentage of rolling twelve-month revenue.
- Express pretax net income as a percentage of the same revenue.
- If trade capital percentage is lower, the company is in the cash-free growth zone. If higher, estimate how far current cash and credit will carry growth before a pause is needed.
- Model the effect of one terms change, such as ten fewer receivable days or ten more payable days, on the gap between the two percentages.
Growth targets are set with a known cash consequence. The CFO and CEO stop being surprised when a strong sales quarter drains the bank account.
3. Launch Capital Ledger
Crabtree argues that growth bets fail quietly because they are never separated from ongoing costs. The ledger makes each bet visible and sets the profit increase it must deliver. Start it whenever the company adds people ahead of demand, launches a marketing push, opens a location, or hires consultants for a transition.
How it works:
- List every spend in the current year that was not needed to sustain the business at its prior level, including staff kept or added ahead of demand.
- Total the list as the year’s launch capital.
- Set the required increase in annual pretax profit at fifty percent of that total, and name the year by which it must show up.
- Review rolling three-month contribution margin each month to see whether the bet is pacing toward the target.
- At the deadline, compute the actual return and decide whether to continue, resize, or stop each bet.
Each growth initiative has a dollar target and a date. Leaders talk about whether a bet is paying back rather than whether a cost overran a budget line.
4. Labor Efficiency Baseline
The labor efficiency ratios are the book’s main management tool and the basis for hiring caps and raise ceilings. They only work if labor is classified consistently and measured on rolling data. Set the baseline before the next compensation cycle or the next request for headcount.
How it works:
- Classify every employee as direct labor or management labor using the whole-person rule. Anyone spending half or more of their time on what the company sells is direct labor.
- Strip payroll tax and benefits out of wages and track them as a separate pool.
- Calculate direct labor efficiency as gross margin divided by direct labor, and management labor efficiency as contribution margin divided by management labor, on rolling twelve months.
- Find the record value of each ratio in the company’s own history.
- Adopt the records as the standard. No new hire or raise in a group until that group’s ratio meets the standard for the quarter.
Headcount and pay conversations reference a shared number. Managers arrive with the ratio already calculated when they ask for a new hire.
5. Segment Return Review
Crabtree shows that the largest segment by revenue is often not the best investment. Reporting each product, location, or team at gross margin and contribution margin, then adding the capital each consumes, shows where to scale. Run the review annually and before any decision to expand a location, product line, or service team.
How it works:
- Choose the segments that match how the company sells: locations, divisions, service models, or major customers.
- Report each segment to contribution margin without allocating overhead.
- Add the trade capital and buildout or equipment capital each segment ties up.
- Calculate return on that capital for each segment and rank them.
- Name one segment to expand, one to fix, and one to reprice or exit.
Expansion debates move from which leader is most persuasive to which segment earns the most on its capital. Segment leaders see the numbers they control without opening every cost to discussion.
6. Replacement Return Test
Crabtree’s keep-or-sell test asks what yield the after-tax sale proceeds would need to earn to replace the profit the owner gives up. It keeps an attractive multiple from driving a decision the economics do not support. Run it when an unsolicited offer arrives, when partners discuss a buyout, or as part of annual exit planning.
How it works:
- Estimate the after-tax proceeds at the offered price, net of transaction costs and any earnout risk.
- Take the business’s current annual pretax profit after a market wage for the owner.
- Divide the profit by the after-tax proceeds to get the required replacement return.
- Compare that return to what the owner can realistically earn elsewhere. Crabtree uses eight to fifteen percent for real estate.
- If the required return is above fifteen percent, write down the noneconomic reasons for selling and decide whether they justify the gap.
Sale conversations separate economics from emotion. The owner can explain why an offer is or is not enough in terms a spouse, partner, or buyer can follow.
Further Reading
- Greg Crabtree’s Simple Numbers site, with current tools and the labor efficiency approach as his team now teaches it.
- Greg Crabtree on the four Simple Numbers measures, from his own blog.
- McKinsey on choosing between growth and ROIC, the public company research behind the growth versus returns tradeoff.
- John Mullins, The Customer-Funded Business, which Crabtree cites on growing from customer cash instead of investor cash.
- Greg Crabtree interviewed by Monkhouse and Company on labor efficiency ratio and launch capital.
Share This Review
Bruce Eckfeldt is a business coach and strategic advisor to founder-CEOs of growth-stage companies, a former Inc. 500 CEO, and the author of Springboard. More book reviews →
These summaries present Bruce Eckfeldt’s analysis of business and leadership books for founder-CEOs and leadership-team members of growth companies. Each one identifies the ideas most relevant to decision quality, strategy, and leadership capacity, notes where the evidence is weak, and suggests practical ways to test what is worth testing. All ideas, stories, and quotations belong to the original author and to the people they cite. The assessments and recommendations are Bruce’s. It is a companion to the book, not a substitute for reading it.
To learn more about Bruce’s programs, request other book summaries, or get in touch, contact booksummaries@eckfeldt.com.
Get the Next Review.
A new book review lands in Better, Faster, my weekly newsletter for founder-CEOs, along with one practical essay and questions for your team.